Evidence determines access. Access determines value.
Europe is more than another market — done right, it adds value to your asset worldwide. Evidence strategy, HTA, pricing and reimbursement for biotech, including US and Chinese innovators.
Why Europe matters
There’s a fallacy that Europe is the commercial poor relation of the US. On revenue, perhaps — but strategically, Europe is often the more accessible gateway: a regulatory route into the Middle East and other markets, and, increasingly, the registration path Chinese innovators choose for global development and licensing.
Europe is where your asset earns the evidence, the price and the credibility that travel with it worldwide.
Approval opens the door; value is won after it.

The rules just changed — and the panic is mostly wrong.
Since 2025, Europe's Joint Clinical Assessment (JCA) decides whether national payers actually reward your evidence. Approval is not access — in the average European country, only about half of newly approved medicines reach patients.
At the same time, US Most-Favored-Nation (MFN) pricing has companies delaying European launches to protect their US price. But the finalised rules are far narrower than the headlines:
- the GLOBE model is limited by therapeutic category, a $100M Medicare Part B threshold, and exclusions for orphan, cell & gene, plasma-derived and IRA-negotiated products
- and GUARD is not yet final. Many biotechs have little direct exposure.
So before you postpone Europe, do you know how much US revenue are you actually protecting — and how much European revenue are you giving up? Most companies can't answer that with a number. That's what I do.
(EU HTA Regulation (EU) 2021/2282 —
https://eur-lex.europa.eu/eli/reg/2021/2282/oj)

Built for emerging biotech
Roche and Novartis have floors of in-house HTA specialists. You don't, and you don't need them full-time. I'm the specialist you bring in for the questions that decide your value:
- Will your trial win a strong added-benefit rating?
- What price will it actually command across European markets?
- What is the asset really worth once JCA and MFN are priced in?
I connect the evidence to the value — the piece that your strategy cannot miss.
How Sur Access can help

Global Pricing & Market Access
Know what your asset can command in Europe — and what it’s really exposed to. I size your pricing potential, plan launch sequencing, and put a number on your US MFN and international reference-pricing risk before you commit to a market or a date.
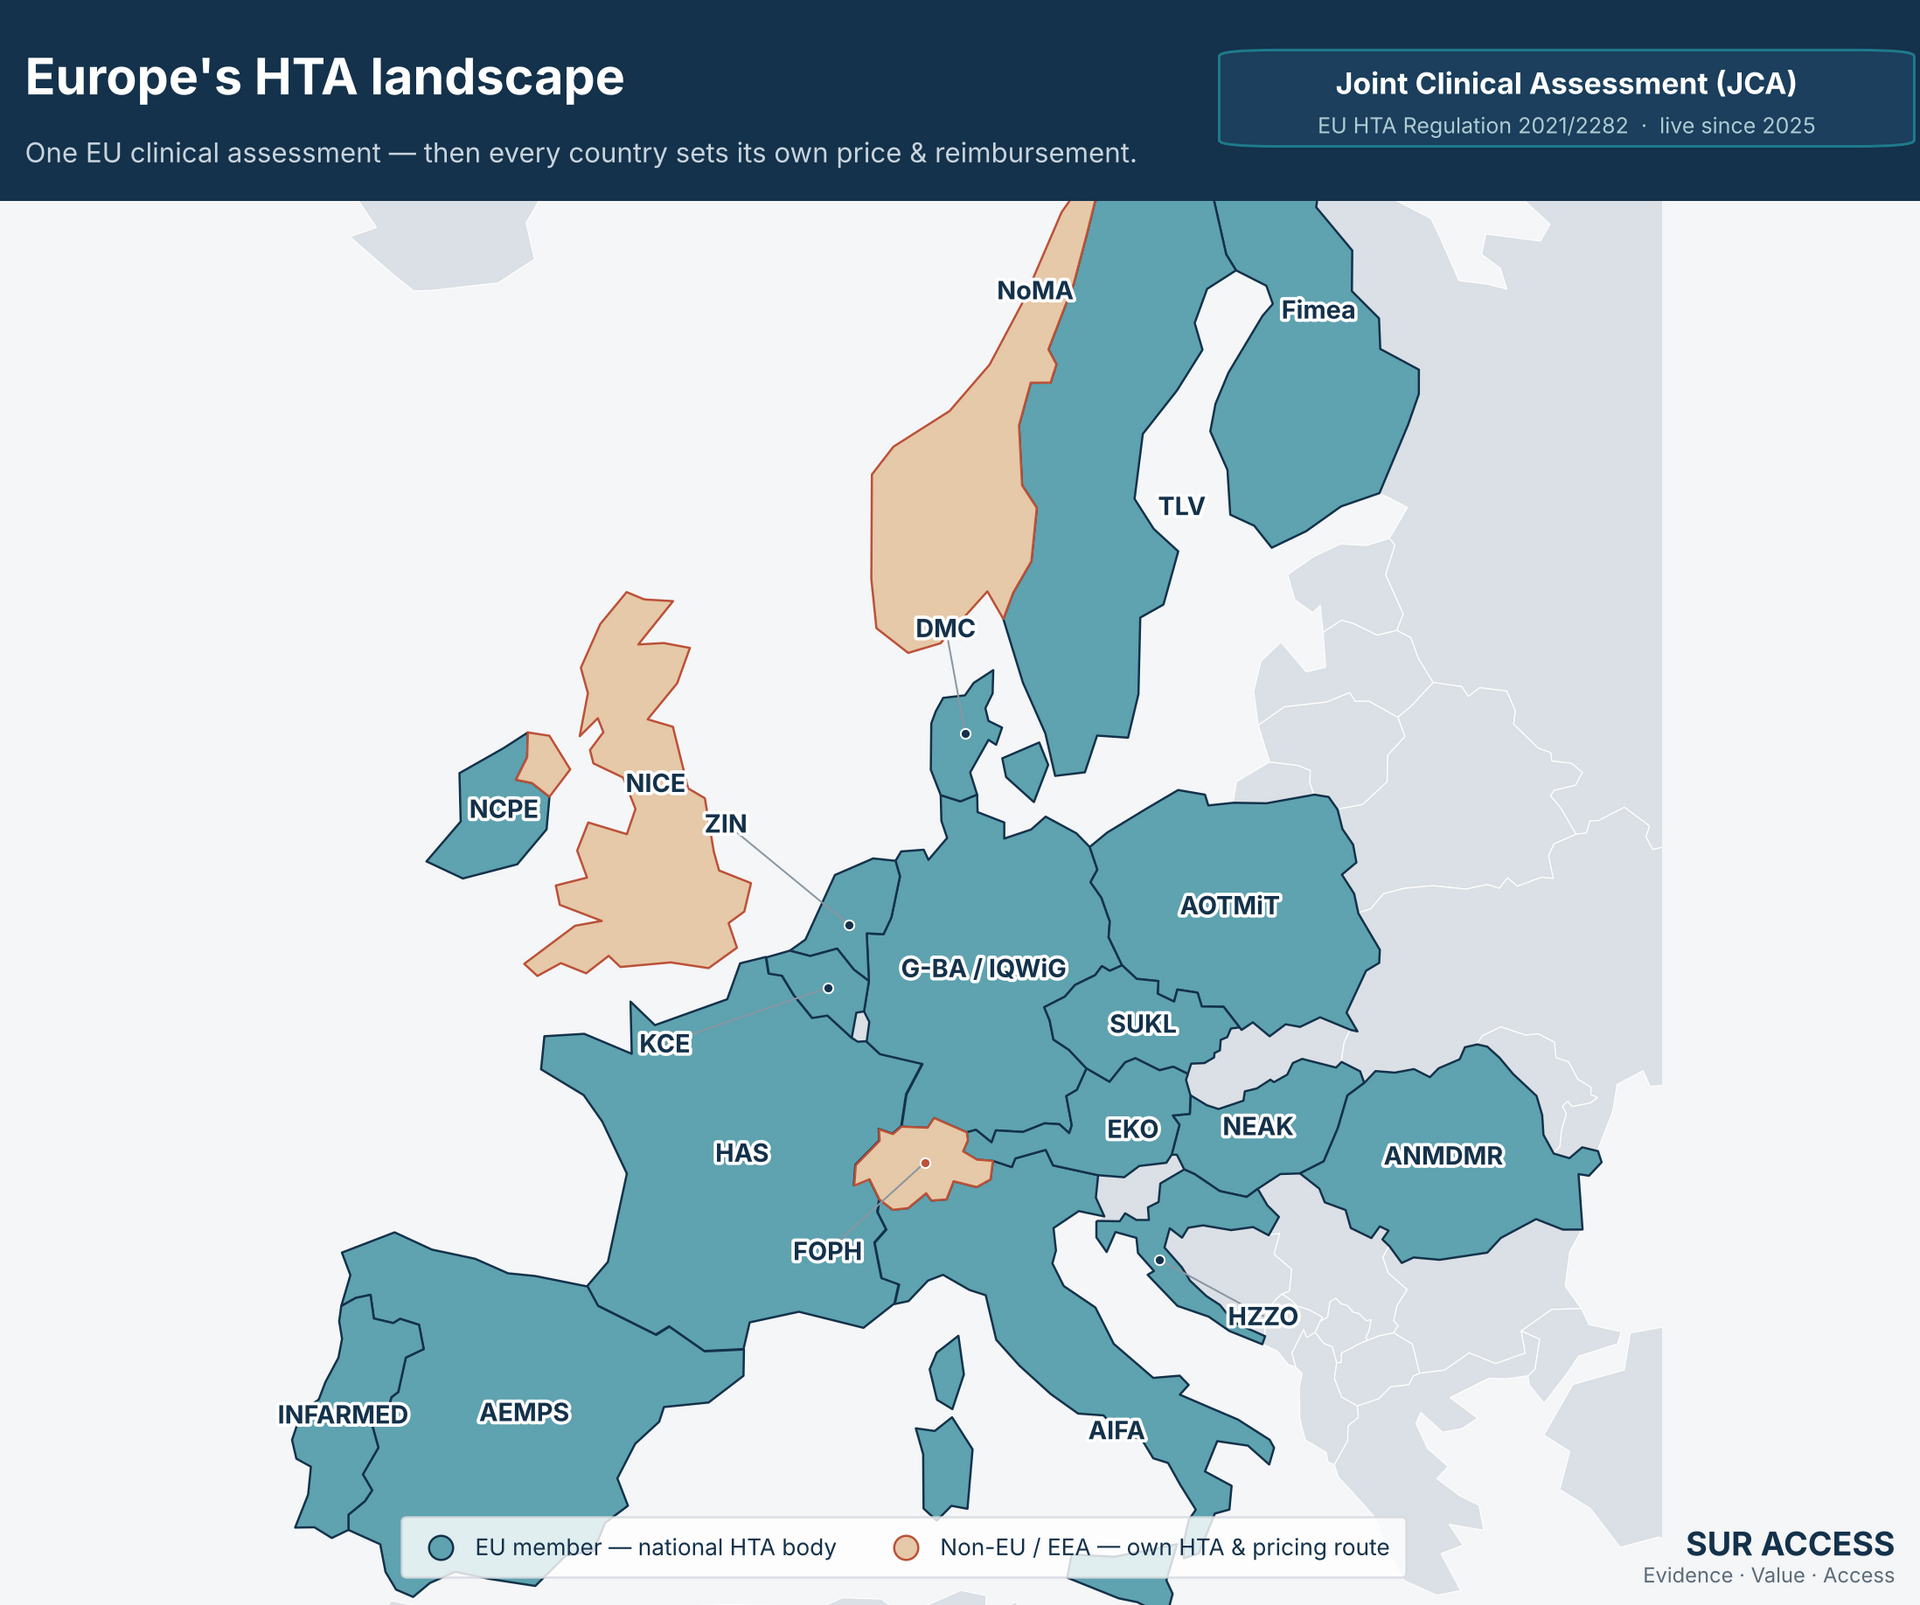
EU HTA & JCA
JCA readiness, PICO strategy, comparative evidence planning, indirect comparisons and dossier support.

Swiss Pricing & Reimbursement
Switzerland can be your earliest European launch and a confidential price anchor the rest of the world can’t reference. I guide your BAG/FOPH dossier, your TQV/APV pricing and provisional reimbursement so you reach patients — and revenue — sooner.

Croatian Market Access
Croatia is one of Europe’s most underused EU entry points — faster, lower budget impact, and a pricing precedent that shapes the wider CEE region. I run your HZZO reimbursement and sequencing so a small market becomes a deliberate lever, not an afterthought.
Our Partners Trust Our Approach
